Horizon Media President Bob Lord Challenges Agency Labor-Based Pricing Models in Shift Toward Composable Architectures

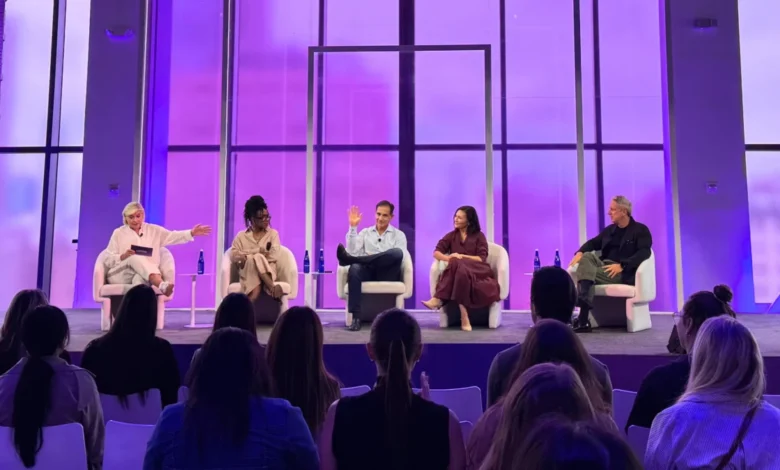
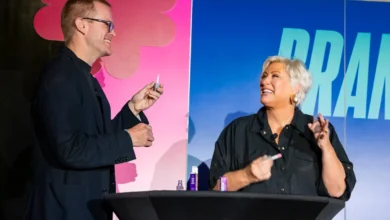
The advertising industry currently finds itself at a significant crossroads, caught between the traditional legacy of service-based revenue models and the rapid, technology-driven evolution of modern marketing. During the recent Smartly Advance event held in Lower Manhattan, Bob Lord, president of Horizon Media Holdings, ignited a conversation that has long been whispered in boardrooms but rarely addressed with such directness on a public stage: the systemic obsolescence of labor-based pricing.
Lord’s critique centered on the reliance of large holding companies on Full-Time Equivalent (FTE) models and principal-based buying, which he argued act as institutional anchors preventing the industry from achieving true agility. As marketing technology becomes increasingly sophisticated, Lord posited that the agency world is suffering from a misalignment between its cost structures and the value it actually delivers to clients.
The Shift from Labor to Composable Architecture
At the heart of Lord’s argument is the concept of "composable architecture"—a modular approach to building marketing ecosystems that allows brands to swap out specific technologies or services as business needs evolve. In this framework, the agency’s role shifts from being a monolith of services to a strategic partner that integrates best-in-class tools.
However, Lord identified a primary antagonist in the pursuit of this innovation: industry inertia. "What’s holding us back? Inertia," Lord stated during his session. He argued that the current economic structure of large agency groups is fundamentally tied to the number of bodies they can bill to a client. When an agency’s profitability is pegged to the number of FTEs assigned to an account, the incentive to automate or streamline processes through technology is inherently weakened.
"It’s the old system: FTE-based models, principal-based buying—how the holdcos make their money," Lord noted. He further highlighted that while agencies have spent the last half-decade investing heavily in proprietary technology stacks, those investments are often "forced" onto clients as part of a bundle, regardless of whether those tools are the most effective solution for the client’s specific business objectives. For Lord, this is not a personal grievance against competitors, but rather an observation of a fundamental economic equation that no longer serves the modern advertiser.
Chronology of an Industry in Transition
The tension between service-based pricing and tech-enabled efficiency has been mounting for years. The timeline of this transformation can be viewed through several distinct phases:
- 2010–2015: The Rise of Agency Tech Stacks. Following the 2008 recession, holding companies began aggressively acquiring data and ad-tech firms to remain competitive against emerging digital platforms. This period was characterized by the consolidation of buying power and the growth of large, centralized service hubs.
- 2016–2020: The Transparency Crisis. A series of industry reports—most notably the 2016 ANA (Association of National Advertisers) report on media transparency—raised concerns about undisclosed rebates and principal-based buying, forcing agencies to defend their margins.
- 2021–2023: The Pandemic Pivot. The sudden shift to digital-first commerce during the pandemic forced brands to demand higher accountability and faster deployment of technology, exposing the slow speed of legacy agency structures.
- 2024–Present: The AI and Composable Era. Generative AI and automated workflow tools have begun to decouple human labor from marketing output. Agencies are now facing a reality where "hours worked" is an increasingly poor proxy for the value of an algorithm-driven campaign.
Supporting Data: The Cost of Complexity
The economic argument against FTE-based models is supported by broader shifts in the agency-client relationship. According to data from the World Federation of Advertisers (WFA), the average tenure of a Chief Marketing Officer has remained stagnant or declined, leading to shorter-term strategic views that often prioritize cost-cutting over long-term transformation.
Simultaneously, a 2023 industry study indicated that nearly 60% of major brands are currently reviewing their agency rosters, citing a desire for greater transparency and technical integration. As brands bring more media buying and creative production in-house, the "agency of record" model, which relies on high-volume staffing, is facing a shrinking total addressable market.
Furthermore, the rise of "unbundled" services suggests that clients are increasingly looking for modularity. While a decade ago a single holding company might handle all media, creative, and data operations, today’s brands are opting for specialized, independent agencies that can plug into a "composable" framework. Horizon Media, as an independent entity, has positioned itself to capitalize on this trend by eschewing the rigid structures of the publicly traded conglomerates.
Industry Perspectives and Official Reactions
While Lord’s comments at Smartly Advance were framed as an objective analysis of economic incentives, the reaction from the broader industry has been nuanced. Representatives from major holding companies have traditionally defended the FTE model as a mechanism for stability.
"The FTE model provides a predictable structure for talent retention," noted one agency executive who requested anonymity to speak candidly about industry pricing. "When you are managing global campaigns across 50 markets, you need a high level of human oversight that technology alone cannot provide. To move entirely to a value-based or outcome-based model, you would need a level of client trust and data sharing that, frankly, many brands are not yet prepared to offer."
However, others in the independent sector have echoed Lord’s sentiment. The consensus among smaller, tech-forward agencies is that the industry is currently in a state of "valuation capture," where agencies are trying to recoup their massive capital investments in proprietary tech by locking clients into long-term, non-transferable agreements. This creates a "walled garden" effect, which is precisely the kind of rigidity that Lord’s composable architecture seeks to dismantle.
Broader Implications for the Future of Advertising
The implications of moving away from labor-based pricing are profound. If the industry shifts toward value-based pricing—where agencies are compensated based on performance, business outcomes, or project-based milestones—the entire recruitment and retention strategy for agency talent will need to change.
- The Talent War: Currently, agencies hire to grow revenue, with headcount being a direct driver of billables. In a value-based world, agencies would prioritize smaller, highly skilled teams capable of managing sophisticated AI workflows. This would likely lead to higher wages for specialized roles but a smaller overall workforce.
- Tech Neutrality: For composable architectures to work, agencies must act as objective consultants rather than vendors pushing their own internal tools. This creates a conflict of interest that holding companies, who own both the service and the software, must navigate.
- Client-Agency Trust: The most significant hurdle is the requirement for deep data integration. For an agency to be paid based on business growth, they must have visibility into the client’s bottom line—data that many corporations consider highly sensitive.
Lord’s message is ultimately a call for a paradigm shift. As the advertising industry matures, the value proposition is moving away from "how many people are working on this" toward "how well does this architecture perform." For firms like Horizon Media, the strategy is clear: position the agency as a flexible orchestrator of technology rather than a human-heavy service provider.
Conclusion: Navigating the Inertia
The "economic equation" Lord highlighted is one that will likely dominate industry discourse for the foreseeable future. As the integration of artificial intelligence accelerates, the friction between legacy revenue models and modern operational efficiency will only increase.
The next few years will serve as a testing ground. Agencies that can successfully transition to value-based, modular, and technology-agnostic models may find themselves leading the next wave of industry standards. Conversely, those that remain tethered to the volume-based FTE models of the past risk being bypassed by brands seeking agility, transparency, and, above all, measurable business outcomes.
For the industry professionals gathering in Midtown this October at Adweek House, the conversation initiated by Lord serves as a timely reminder: the tools of the future cannot be effectively deployed using the pricing models of the past. The industry is standing at a point of no return, where the survival of the traditional agency model may well depend on its willingness to fundamentally redefine how it charges for its most valuable asset: its ability to drive growth in a complex, digital-first world.
Related posts: