The Rise of Synthetic Expense Fraud: AI-Generated Receipts Now Dominate Flagged Submissions

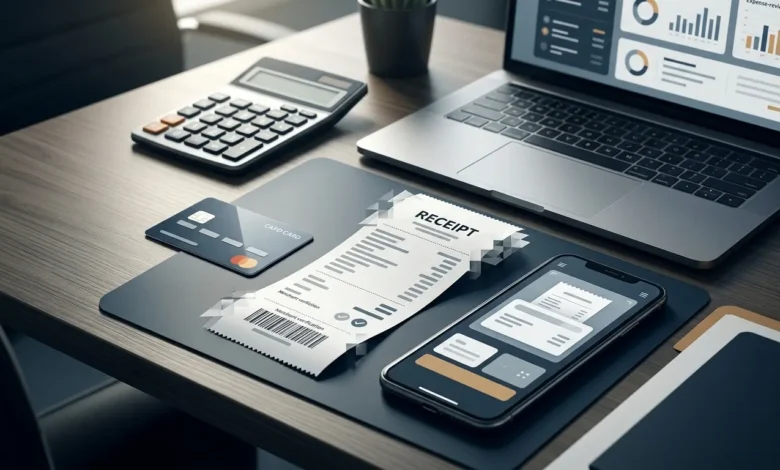
The landscape of corporate expense management has undergone a profound and rapid transformation, driven by the widespread accessibility of generative artificial intelligence. According to recent platform data released by expense-management vendor AppZen and reported by Accounting Today, AI-generated receipts now account for a staggering 70.8% of all flagged fraudulent expense submissions. This figure represents an extraordinary climb from 0% in March 2025, illustrating how quickly bad actors have capitalized on emerging technology to fabricate financial documents.
The data underlying this finding is drawn from a specific detection pipeline covering 174 companies between March 2025 and mid-May 2026. Within this sample, the platform identified 1,471 AI-generated fake receipts submitted by 745 individual employees, successfully claiming a combined total of $148,143 in fabricated reimbursements. Industry experts emphasize that this metric does not represent an overall increase in total macroeconomic workplace fraud; rather, it highlights a definitive shift in the methodologies utilized by employees already inclined toward expense abuse. As generative AI tools have become more sophisticated and readily available, traditional template-based forgeries have been rapidly eclipsed by synthetic documents that bypass standard visual checks.
This technological pivot is further corroborated by independent employee-sentiment research. An expansive survey conducted by Atomik Research between May 5 and May 8, 2026, commissioned by expense platform Emburse and detailed by PYMNTS, polled 2,000 workers across the United States and the United Kingdom. The findings revealed that 40% of U.S. respondents and 29% of U.K. respondents candidly admitted to utilizing artificial intelligence to generate a fake business-expense receipt. Drilling deeper into the survey data, 40% of those admitting to the practice reported using company-funded AI tools to produce the documents, while 9% went so far as to build their own custom tools specifically designed for the task.
The Chronology of a Financial Shift
To understand the current crisis in expense governance, one must examine the timeline of how synthetic fraud penetrated corporate systems. Prior to early 2025, digital expense fraud predominantly relied on static templates, basic photo-editing software, or the digital alteration of genuine receipts. These older methods often left discernible forensic clues for corporate bookkeepers, such as mismatched typefaces, distorted company logos, and misaligned numerical columns.
By early 2025, commercially available generative AI image tools began to mature, lowering the technical barriers required to produce hyper-realistic documents. Throughout 2025, security vendors observed a gradual integration of these tools into illicit expense workflows. However, the true tipping point occurred in April 2026, when AppZen’s analytics recorded that AI-generated receipts officially surpassed template-based fakes in volume among flagged submissions. By mid-May 2026, synthetic receipts had completely monopolized the upper tier of flagged fraudulent activity, reaching the 70.8% threshold.
This rapid ascent underscores a broader challenge for modern compliance officers: the democratization of high-level forgery. Employees no longer require graphic design proficiency to create a convincing, itemized invoice from a high-end restaurant or a boutique hotel. Modern AI image generators can seamlessly render complex textures, precise localized tax calculations, and authentic merchant-style layouts in a matter of seconds.
Anatomy of the Fraud: Intent, Demographics, and Ticket Sizes
Analyzing the psychological and operational profiles of the perpetrators reveals diverse motivations. According to the Emburse survey data, the workers who admitted to utilizing AI for receipt generation fell into three distinct behavioural categories, each carrying a different risk profile for corporate finance departments: 19% fabricated entirely fictitious purchases that never occurred; 15% inflated the actual monetary value of a legitimate business expense; and 6% recreated authentic receipts for genuine business purchases where the original paper documentation had been lost.
For corporate finance teams, treating these three behaviors as identical can lead to flawed disciplinary and procedural responses. While deliberate theft requires strict punitive action, recreating a lost receipt—though still a violation of accounting controls—stems from administrative frustration rather than malicious enrichment.
Furthermore, the financial footprint of synthetic fraud exhibits a strategic pattern designed to evade detection. AppZen’s platform data indicates that AI-generated fakes captured within their pipeline command a relatively modest average claim size of approximately $100, with a median value of just $32. In contrast, older template-based fakes averaged $182. This discrepancy reveals that bad actors are deliberately deploying synthetic receipts for high-volume, low-dollar transactions. These amounts frequently fall safely beneath automated corporate approval thresholds, allowing fraudulent claims to slip past the routine scrutiny typically reserved for larger, more conspicuous travel and entertainment reimbursements.
The Vulnerability of Small-Business Finance Teams
While enterprise-level corporations often maintain dedicated internal audit departments, tiered managerial approvals, and sophisticated fraud-detection software integrated directly into their expense platforms, small and mid-sized businesses (SMBs) face a drastically different operational reality.
In many smaller companies, a single individual—such as a business owner, office manager, or sole bookkeeper—is tasked with reviewing employee expense reimbursements while simultaneously managing payroll, accounts payable, vendor relations, and daily scheduling. Under these conditions, finance personnel have minimal time to investigate a seemingly routine $32 lunch receipt or a $100 travel claim.
This vulnerability is frequently compounded by shared corporate card programs, outsourced accounting firms operating on delayed schedules, and informal managerial approval chains. When low-dollar synthetic submissions are filed incrementally by the same employee over several months, they blend harmlessly into the background noise of regular operating expenses. However, the cumulative financial leakage can be substantial, and the long-term accounting implications extend far beyond the immediate reimbursement payout.
A fraudulent or improperly documented expense can distort internal tax records, compromise job-cost accounting, create inaccuracies in client billing, and misstate financial statements. Correcting these discrepancies retroactively consumes valuable administrative hours that resource-constrained small businesses simply cannot spare.
Re-Engineering Expense Controls for the AI Era
The empirical data from AppZen and Emburse leads to a singular, inescapable conclusion for the accounting profession: the traditional visual-review workflow—where a human manager or bookkeeper inspects a static image of a receipt and approves reimbursement—is officially obsolete.
As synthetic generation makes visual authenticity an unreliable metric, organizations must modernize their internal controls to verify transactions through independent, non-visual data points. Industry experts recommend several critical adjustments for finance teams preparing for upcoming reimbursement cycles:
First, businesses must implement automated transaction-matching protocols. By integrating expense-management software directly with corporate credit card feeds and banking APIs, finance systems can automatically cross-reference submitted receipt images against real-time financial institution data, instantly flagging discrepancies in amounts, dates, and merchant identities.
Second, organizations should enforce strict merchant verification standards. Automated tools can cross-check listed vendors against verified registries, ensuring that the issuing business actually exists, operates at the stated location, and possesses a legitimate tax identification number.
Third, finance teams must deploy repeat-pattern monitoring algorithms. Because synthetic fraud often relies on frequent, low-dollar submissions, monitoring cumulative claims by individual employees over rolling timeframes can expose abnormal behavioral anomalies that individual receipt reviews miss.
Finally, companies must establish explicit, unambiguous corporate policies regarding the use of generative artificial intelligence, making it clear that the submission of synthetic or altered financial documentation constitutes grounds for immediate termination and potential legal action.
Broader Implications and Future Outlook
The rapid normalization of synthetic receipt fraud marks a permanent inflection point in financial governance. The transition from 0% to nearly 71% of flagged fraud within a span of roughly fourteen months demonstrates that financial fraudsters are among the earliest and most effective adopters of generative technology.
As artificial intelligence capabilities continue to advance, the burden of proof in expense management will definitively shift away from document appearance and toward algorithmic verification. For businesses of all sizes, the message is clear: robust internal controls must evolve to assume that any digital image can be perfectly forged. By moving beyond visual inspection and embracing data-driven validation, finance teams can safeguard their organizations against the growing wave of synthetic financial crime.
Related posts: