Major Overhaul of State Pension Triple Lock and Introduction of National Care Service to Reshape Retirement Planning by 2030

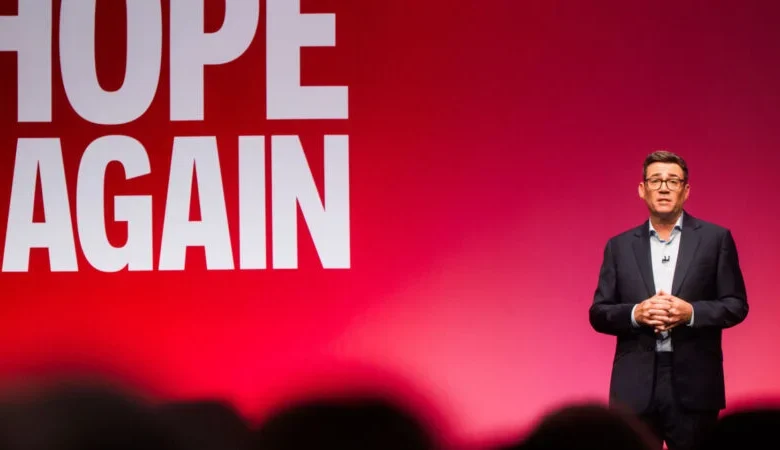
The landscape of British retirement planning is set for a seismic shift as Prime Minister Andy Burnham announced a fundamental restructuring of the state pension triple lock, scheduled to take effect in April 2030. Speaking at the annual Labour Party conference, the Prime Minister outlined a long-term strategic vision that balances the fiscal sustainability of the state pension with the urgent requirement for a comprehensive National Care Service. While the government has pledged to maintain the existing triple lock mechanism throughout the duration of the current Parliament, the post-2030 framework represents a significant departure from the current uprating system, aiming to trade potentially uncapped pension growth for a robust social care safety net.
The Evolution of the Triple Lock: A Historical Context
The state pension triple lock has been a cornerstone of UK economic policy since its introduction in 2010. Designed to prevent pensioner poverty, the policy mandates that the state pension increases annually by the highest of three metrics: the Consumer Prices Index (CPI) inflation, average earnings growth, or a fixed 2.5 percent. While the mechanism has successfully shielded older generations from inflationary shocks—most notably during the cost-of-living crisis—it has faced increasing scrutiny from economists and policy analysts.
Critics have long argued that the triple lock creates an unpredictable fiscal burden on the Treasury, particularly during years of high wage growth or sudden spikes in inflation. By decoupling the pension from a rigid "highest-of-three" structure, the government aims to create a more manageable trajectory for public spending. Projections from the Department for Work and Pensions (DWP) indicate that the current trajectory, if left unadjusted, could lead to unsustainable spending levels. Under the new proposal, the pension will still rise by the higher of inflation or 2.5 percent, with a supplementary mechanism to ensure the payout keeps pace with national prosperity over the long term, albeit without the volatility associated with current earnings-linked spikes.
Chronology of the Policy Transition
The government’s roadmap for these reforms is structured to provide stability in the short term while preparing the infrastructure for the 2030 transition:
- Present Day – April 2030: The government will honour its manifesto commitment, maintaining the current triple lock in its entirety. This period serves as a transition phase for the Treasury to prepare the fiscal foundations for the new system.
- Summer 2027: The independent commission on adult social care, led by Baroness Louise Casey, is scheduled to deliver its final report. This document will be critical in outlining the administrative and operational framework for the planned National Care Service.
- April 2030: The "adjusted" pension uprating mechanism officially commences. Simultaneously, the first phases of the National Care Service are expected to be operational, providing state-funded personal care based on individual need rather than personal wealth.
- 2030s – 2050: The government projects a multi-billion-pound fiscal realignment. By 2049/50, the DWP estimates that the revised system will generate savings of approximately £50 billion in nominal terms compared to the current triple lock model.
Fiscal Implications and Economic Projections
The decision to modify the triple lock is driven by the stark reality of the nation’s ageing demographic. The DWP’s analysis suggests that the savings realized by capping the pension’s growth will be ring-fenced to fund the National Care Service. This is not merely a cost-cutting exercise; it is an attempt to redistribute public funds from direct pension transfers to essential, high-demand services.

However, these projections are subject to the inherent volatility of long-term economic forecasting. Factors such as migration patterns, fluctuating life expectancy, and productivity growth are variables that could alter these outcomes. The Treasury has cautioned that while the £50 billion figure serves as an indicator of the scale of the policy, it should be treated as a strategic projection rather than a guaranteed fiscal outcome. The sensitivity of these models underscores the difficulty of legislating for a population that is living longer and requiring more intensive care.
Industry Reaction and Expert Analysis
The reaction from the financial services and HR sectors has been one of cautious pragmatism. Mark Pemberthy, Benefits Consulting Lead at Gallagher, noted that the move addresses a "fundamental sustainability issue" while acknowledging the psychological shift it represents for the workforce.
"The triple lock has been a success in restoring the value of the state pension, but we have reached a point where the intergenerational burden has become a significant concern," Pemberthy remarked. "Burnham’s proposal essentially swaps a potential ‘lottery’ of high pension increases for a guaranteed floor of care protection. For most employees, the anxiety of potentially facing £100,000 in care costs—a reality for one in seven people under the current system—is a far greater financial threat than a slightly more modest pension increase."
From a human resources perspective, the reform necessitates a shift in how employers communicate retirement benefits. As employees look toward 2030, the focus of pension planning may move away from solely maximizing state-funded income and toward understanding how the National Care Service will interact with private pension pots and personal savings. HR departments are now faced with the challenge of helping staff navigate this transition, ensuring that workers understand the "deal" being proposed by the government: a stable, albeit reformed, state pension in exchange for a reduction in the unpredictable, catastrophic costs of end-of-life care.
The National Care Service: A New Social Contract
The central pillar of the government’s argument is the creation of a National Care Service. Under the current system, the burden of funding care often falls on the individual, leading to the depletion of assets and the forced sale of homes to cover expenses. By shifting the funding model to a state-led system based on need, the government hopes to provide "peace of mind."
The proposed service will cover essential personal care tasks, including bathing, dressing, and support with mobility. Notably, the policy does not extend to covering accommodation costs, a distinction that will remain a key area of interest for housing and social care experts. The phased introduction of this service will be heavily informed by Baroness Casey’s 2027 report, which is expected to address the logistical challenges of scaling a national care infrastructure.
Addressing the "Care Gap"
The statistics surrounding adult social care in the UK are sobering. Currently, approximately three-quarters of adults over the age of 65 will require some form of social support. The uncertainty surrounding these costs has historically made retirement planning a precarious exercise. Without a state-backed guarantee, individuals have been forced to "over-save" in case they fall into the one-in-seven category of people facing costs in excess of £100,000.
By providing a clear framework for care, the government argues that it is simplifying the financial equation for retirement. If the National Care Service delivers on its promise, it could theoretically allow individuals to plan with more confidence, knowing that the most unpredictable variable in their later-life budget—care costs—has been mitigated by the state.
Conclusion: A Shift in Retirement Strategy
The announcement by Prime Minister Burnham marks the beginning of a long-term adjustment in the UK’s social contract. By 2030, the era of the uncapped triple lock will end, replaced by a system that prioritizes stability and the provision of services over index-linked cash increases. For the current workforce, the implication is clear: the state will remain a primary pillar of retirement, but its role is being redefined.
The success of this policy will depend heavily on the government’s ability to execute the National Care Service effectively. If the service is underfunded or lacks the capacity to meet the needs of the ageing population, the reduction in pension uprating will be viewed as a net negative. Conversely, if the system successfully removes the "fear factor" of care costs, it could represent a significant modernization of the welfare state. As the country moves toward 2030, the focus will now turn to the 2027 commission report, which will likely serve as the blueprint for the final implementation of these profound changes. For HR professionals and financial planners, the mandate is to ensure that employees are adequately informed, allowing them to adjust their retirement strategies to align with this new, complex, and potentially more secure, future.