Market Volatility Intensifies as Treasury Yields Surge and Crude Oil Prices Spike Amid Middle East Tensions

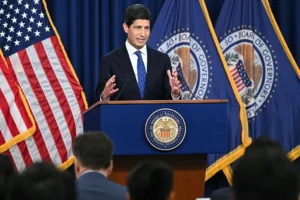
The global financial landscape experienced a turbulent Tuesday as equity markets retreated across the board, weighed down by a relentless climb in Treasury yields and a significant surge in crude oil prices. As the Federal Open Market Committee (FOMC) convened to deliberate on the trajectory of inflation and the future of monetary policy, investors reacted with caution. The three primary U.S. equity benchmarks—the Dow Jones Industrial Average, the S&P 500, and the Nasdaq Composite—opened in negative territory and failed to recover, ending the trading session lower as the market braced for the central bank’s impending interest rate decision.
The volatility was underscored by a pronounced sell-off in fixed income, as investors demanded higher premiums for holding government debt. The 10-year Treasury yield, a critical benchmark for borrowing costs across the economy, reached an intraday peak of 5.041%, marking its highest level since 2007. Although the yield retreated slightly to close at 5.002%, it still registered a 4.1-basis-point increase. Similarly, the 2-year Treasury yield, which is highly sensitive to Federal Reserve policy expectations, hit a new 52-week high, climbing 3.7 basis points to 4.671%. The long end of the curve also saw upward pressure, with the 30-year Treasury yield rising 3.9 basis points to 5.367%.
Energy Markets and Geopolitical Risk
Compounding the pressure on equities was the sharp rise in energy costs. West Texas Intermediate (WTI) crude oil futures surged 4.5% during the session, peaking at $106.75 per barrel before settling at $105.84. This rally was largely driven by escalating geopolitical instability in the Middle East. According to reports from Bloomberg, a land-based pipeline intended to bypass the strategically vital Strait of Hormuz was struck by an Iran-backed militant group.
The attack on Saudi infrastructure highlights the vulnerability of global energy supply chains. The Strait of Hormuz is the world’s most important oil transit chokepoint, and any disruption to alternative export routes places immediate upward pressure on global prices. Analysts suggest that if the conflict in the region persists, the resulting supply-side shock could complicate the Federal Reserve’s efforts to anchor inflation, as energy prices are a primary component of headline Consumer Price Index (CPI) calculations. Chevron (CVX) was a notable outlier in the Dow, gaining 2.6% as energy producers benefited from the higher price environment, continuing a trend of outperformance in the sector throughout the 2026 fiscal year.
The Federal Reserve’s Dilemma
The timing of the current market volatility is particularly significant, as the FOMC’s September policy meeting approaches its conclusion. Financial markets are currently operating under the assumption that a pivot is imminent. Data tracked by the CME FedWatch Tool indicates a 94.5% probability that the Federal Reserve will implement a 25-basis-point rate cut at the end of the meeting on Wednesday afternoon. This represents an increase in market confidence from the 93.5% probability observed on Monday.
The challenge for the Fed is balancing the need to stimulate a cooling economy against the persistent threat of inflationary pressures, exacerbated by rising energy costs. While a rate cut is widely anticipated, the accompanying statement from the committee and the updated "dot plot" of projections will be scrutinized for signals regarding the pace and duration of future easing. The sustained elevation of Treasury yields suggests that the bond market remains skeptical that inflation will return to the Fed’s 2% target without further intervention or a significant economic slowdown.
Corporate Sentiment and the AI Narrative
In the equity space, performance was bifurcated by industry and individual corporate narratives. The Dow Jones Industrial Average fell 0.6% to close at 52,092, while the S&P 500 dropped 0.5% to 7,585, and the Nasdaq Composite shed 0.8% to reach 25,981.
Despite the broader market decline, Nvidia (NVDA) managed a 0.6% gain, standing out as one of the few Dow components to remain in the green. The move followed a public conversation between CEO Jensen Huang and President Donald Trump, held during the All-In podcast event. The discussion served as a coordinated effort to address growing public and regulatory anxiety regarding the rapid proliferation of artificial intelligence. President Trump dismissed concerns about the speed of AI deployment as a "hoax," while Huang emphasized the competitive necessity of the technology, stating, "everybody wins in the AI race in America."
Market observers noted that this dialogue was aimed at stabilizing investor sentiment, which had been shaken by recent "doomsday" warnings regarding the existential risks of AI. Louis Navellier of Navellier & Associates offered a bullish perspective on the sector, noting that the order backlogs for data centers currently extend well into 2032, providing a long-term buffer against short-term regulatory or social headwinds.
Financial Sector Headwinds
Conversely, the financial sector faced significant pressure, with Goldman Sachs (GS) falling 1.2%. The decline followed cautious commentary from Bank of America (BAC) CEO Brian Moynihan regarding third-quarter trading and investment banking activity. As banks represent the engine of the financial system, their outlook often serves as a proxy for broader economic activity. The market’s reaction to Moynihan’s remarks indicates a heightened state of sensitivity ahead of Goldman Sachs’ own management presentation at an upcoming industry conference, where analysts expect further clarity on revenue volatility.
Semiconductor Consolidation: Skyworks and Qorvo
The semiconductor sector provided a rare bright spot of volatility. Skyworks Solutions (SWKS) surged 13.6%, recovering from a steep loss in the previous session. The rally followed a period of intense focus on the company’s planned acquisition of Qorvo (QRVO). The $22 billion merger, which was first announced last October, is expected to close by the end of 2026.
Skyworks CEO Philip Brace has been vocal about the deal’s potential, describing it as "transformative." By combining their operations, the companies aim to solidify their position as leaders in radio frequency and mixed-signal semiconductors. The move is particularly strategic as it diversifies their exposure to the aerospace and defense sectors, moving beyond their traditional reliance on consumer electronics and the mobile phone market. Qorvo shares also rallied, closing up 9.3% on the day.
Axon Enterprise and Debt Financing
In the industrial sector, Axon Enterprise (AXON) faced a difficult session, closing down 9.8%. The decline was triggered by management’s announcement of a $1 billion offering of 0% senior convertible notes. While convertible debt is a common tool for funding growth, the market reacted negatively to the potential for shareholder dilution.
Axon plans to use a portion of the proceeds to enter into "capped call" transactions, which are designed to mitigate the dilution effect on current shareholders. The remaining funds are earmarked for general corporate purposes, including potential acquisitions. Despite the single-day drop, institutional support for the stock remains robust; S&P Global Market Intelligence reports that 18 analysts maintain a "Buy" rating on the stock, compared to only three "Hold" ratings, suggesting that investors view the price drop as a potential entry point rather than a fundamental change in the company’s growth trajectory.
Implications for the Near Term
The events of Tuesday illustrate the precarious position of global markets in late 2026. The intersection of a central bank at a policy crossroads, a volatile energy market sensitive to geopolitical shock, and a tech sector attempting to manage its public image creates a complex environment for capital allocation.
As the FOMC meeting concludes on Wednesday, the primary focus will be on the "terminal rate"—the level at which the committee expects to stop cutting rates. If the Federal Reserve adopts a more hawkish tone than the market expects, or if oil prices continue to climb, the current correction in equities could deepen. Conversely, a clear, data-dependent path toward lower rates could provide the liquidity needed to stabilize markets and support a year-end recovery. Investors are advised to monitor the intersection of Treasury yields and corporate earnings reports, as these will likely remain the primary drivers of market direction in the weeks ahead.