Federal Reserve Rate Hike Triggers Market Volatility Amidst Shifting Economic Outlook

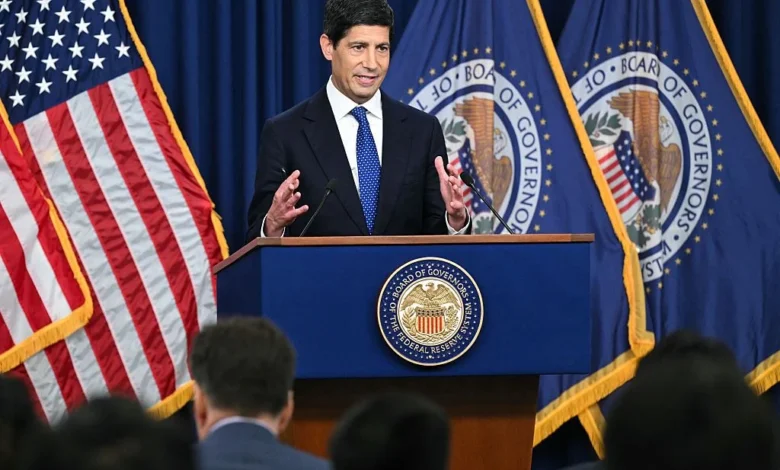
The Federal Open Market Committee (FOMC) delivered a significant policy shift on Wednesday, announcing a 25-basis-point interest rate hike that pushed the federal funds rate target range to 3.75% to 4.00%. This move, the first of its kind in three years, signals a decisive departure from the central bank’s recent period of monetary accommodation. Following the unanimous decision, Fed Chair Kevin Warsh emphasized that the move was necessary to preserve price stability, citing persistently elevated inflation as the primary catalyst for the tightening cycle. As financial markets digested the announcement, major indices retreated, reflecting investor apprehension over the impact of higher borrowing costs on corporate earnings and consumer spending.
Chronology of the Monetary Policy Shift
The decision arrives at a pivotal juncture in the 2026 fiscal calendar. For much of the first half of the year, the Federal Reserve maintained a "wait-and-see" approach, prioritizing economic recovery over immediate inflation containment. However, the recent series of macroeconomic indicators, particularly in the labor market and retail sector, forced the FOMC’s hand.
- Q1 2026: The Fed holds rates steady as officials weigh the risks of geopolitical instability against the need to curb rising price levels.
- June 2026: Signs of robust capital expenditure (capex) and strong corporate productivity emerge, providing the committee with more confidence in the economy’s resilience.
- August 2026: Retail sales data surprises to the upside, showing a 1.2% increase—nearly double the consensus estimate of 0.7%—signaling that consumer demand remains uncomfortably high for the Fed’s inflation targets.
- September 16, 2026: The FOMC formally concludes its two-day meeting with the 25-basis-point hike, simultaneously releasing a Summary of Economic Projections that suggests at least one additional rate increase is likely before the end of the calendar year.
Market Reaction and Investor Sentiment
The stock market’s response to the announcement was immediate and broad-based. By the closing bell, the Dow Jones Industrial Average had shed 1.2% to finish at 51,461, while the S&P 500 declined 0.5% to 7,551. The tech-heavy Nasdaq Composite managed to hover near flat, closing down just 0.01% at 25,978.
Analysts suggest that while the rate hike was largely priced in by sophisticated investors, the underlying message—that the Fed is committed to a multi-step tightening process—created a "repricing" event for risk assets. Adam Turnquist, Chief Technical Strategist at LPL Financial, notes that history provides a mixed but cautiously optimistic roadmap. "Following a rate hike that ended a pause of six months or longer, the S&P 500 has historically gained an average of 5.5% over the subsequent 12 months," Turnquist stated. He cautioned, however, that these periods are often marked by volatility, noting an average maximum drawdown of 9.4% during those same historical windows.
The Economic Backdrop: Consumption vs. Inflation
The Fed’s decision is underpinned by a complex economic landscape. While geopolitical developments have introduced a layer of uncertainty regarding global supply chains, domestic indicators remain surprisingly durable. Productivity remains high, and corporate balance sheets are generally considered robust. However, the strength of the consumer remains a double-edged sword.
Dr. Eugenio J. Alemán, Chief Economist at Raymond James, highlighted the implications of the latest retail sales figures. "While the August data is undeniably positive for immediate GDP growth, it complicates the Fed’s mandate," Dr. Alemán noted. "Strong consumption fuels inflationary pressure. If the American consumer continues to spend at this pace, the Federal Reserve will have little choice but to maintain a restrictive policy stance for longer than the market currently anticipates."
The volatility in Treasury yields further highlights the market’s internal debate. While the 30-year Treasury yield saw a minor dip to 5.356%, the 2-year Treasury yield surged 7.1 basis points to 4.734%, marking a new 52-week high. This "inversion-adjacent" behavior in the yield curve typically indicates that while the short-term outlook for interest rates is aggressive, the long-term outlook remains tethered to fears of a potential economic slowdown.
OpenAI and the Tech Sector Outlook
In the technology sector, the focus remained on private capital valuations. OpenAI, the developer of ChatGPT, is currently in discussions for a new funding round that would push its valuation beyond the $1.2 trillion threshold. This ambition stands in stark contrast to the broader market’s cooling sentiment regarding high-growth, pre-IPO tech companies.
Despite this aggressive valuation pursuit, CEO Sam Altman has signaled a cautious approach regarding a public market debut. In a recent interview, Altman cited ongoing safety concerns and the "ill-advised" nature of an IPO in the current regulatory and economic climate. This suggests that even as private markets assign massive valuations to artificial intelligence leaders, the path to liquidity for these companies remains fraught with operational and macroeconomic hurdles.
The Industrial Struggle: J.B. Hunt and Energy Costs
The impact of the broader economic environment was perhaps most visible in the industrial sector, specifically with logistics giant J.B. Hunt. The company’s stock plunged 13.3% on Wednesday after management provided a rare and negative update on quarterly guidance.
CFO Brad Delco attributed the expected 5% to 10% decline in Q3 earnings to the unprecedented surge in diesel fuel costs. With the national average diesel price hitting a record $6.31 per gallon—a 70.5% increase year-over-year—the company is facing a "mismatch" between its intermodal pricing contracts and the immediate, volatile costs of fuel.
"We are seeing some of the most radical and abnormal swings in fuel prices we have encountered," Delco stated during a presentation at a Morgan Stanley conference. The situation at J.B. Hunt serves as a micro-case study for the broader industrial sector: despite high consumer demand, the inflationary costs of energy and logistics are beginning to erode profit margins, a trend that could become more pervasive across the S&P 500 if energy prices remain at these elevated levels.
Broader Implications and Future Outlook
The Federal Reserve’s pivot toward higher interest rates marks the end of an era of cheap capital. As Chair Kevin Warsh reiterated, the committee’s priority is price stability, even at the cost of short-term market volatility. The "unanimous" nature of the vote provides a clear mandate, suggesting that the Fed is unified in its belief that inflation remains the primary threat to long-term economic stability.
Looking forward, the markets will likely remain hyper-focused on the next round of labor reports and inflation data. If the "resilient" consumer spending mentioned in the FOMC statement begins to wane, the Fed may have the flexibility to slow the pace of future hikes. However, if retail sales continue to exceed expectations, the central bank is prepared to continue its aggressive trajectory.
For investors, the current environment necessitates a shift from speculative growth to quality, value-oriented assets that can withstand higher capital costs. The combination of rising yields, cooling industrial margins, and the ongoing tug-of-war between inflation and economic growth defines the current market regime. As the Federal Reserve moves to tighten the money supply, the focus for the remainder of 2026 will be on whether the economy can achieve a "soft landing" or if the pressure of higher rates will lead to a more significant contraction in corporate earnings.
The path ahead remains uncertain, but the message from the central bank is clear: the era of zero-bound interest rates is firmly behind us, and the market must now adjust to a new standard of monetary policy designed to bring inflation back to target levels, regardless of the short-term turbulence it may induce in the equity markets. Investors are advised to monitor the upcoming quarterly earnings season closely, as it will likely provide the most accurate barometer for how individual firms are navigating the transition from a period of liquidity-driven growth to one of cost-conscious, restrictive monetary policy.
Related posts: