Bose Corporation Announces Strategic Acquisition of Audio Brand Skullcandy to Strengthen Market Position

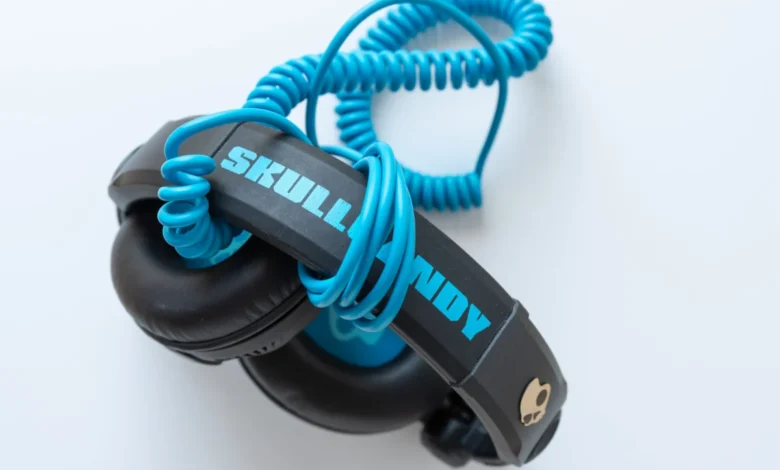
In a significant consolidation within the consumer electronics sector, Bose Corporation formally announced on October 21 its acquisition of Skullcandy, a move that unites two of the industry’s most recognizable names in audio wearables. The transaction represents a strategic expansion for Bose, a privately held titan of acoustic technology, as it seeks to diversify its portfolio and solidify its reach in a rapidly evolving market defined by intense competition from global technology giants.
A Strategic Alignment of Audio Legacies
The partnership between Bose and Skullcandy is not entirely novel. The two companies have a history of collaborative efforts, often involving the integration of Bose’s proprietary audio technologies into Skullcandy’s diverse product lines. By bringing Skullcandy under the Bose corporate umbrella, the acquisition effectively formalizes a relationship that has long existed on a project-by-project basis.
Bose, headquartered in Framingham, Massachusetts, has spent over six decades building its reputation on high-fidelity audio, noise-cancellation research, and premium consumer electronics. Conversely, Skullcandy, born on a chairlift in Park City, Utah, over 20 years ago, carved out a distinct niche by targeting a younger, action-sports-oriented demographic with lifestyle-focused audio gear. This acquisition allows Bose to leverage Skullcandy’s entrenched brand loyalty and unique market positioning while providing Skullcandy with the technical resources and engineering prowess of a global audio leader.
Chronology of Industry Shifts
The audio hardware landscape has undergone a radical transformation over the last decade. Historically, the sector was dominated by specialized audio manufacturers. However, the rise of smartphones and the subsequent demand for sophisticated, feature-rich wearables have drawn major technology companies into the fray.
- 2010s: The Rise of Wearables: As the smartphone market matured, companies like Apple, Samsung, and Sony began aggressively expanding into the audio space. The introduction of advanced features such as active noise cancellation (ANC), transparency modes, and integrated digital assistants transformed headphones from simple accessories into essential digital interfaces.
- 2022: Digital Infrastructure Upgrades: In April 2022, Bose made headlines by selecting Salesforce’s Commerce Cloud to bolster its digital customer experience, signaling a shift toward a more sophisticated direct-to-consumer (DTC) model. Simultaneously, Skullcandy underwent its own digital transformation, migrating its ecommerce operations to Shopify to optimize its retail footprint and enhance the fan-buying experience.
- October 2024: The Consolidation: The formal announcement of the acquisition marks a turning point in the mid-market audio segment. By combining forces, the two entities are positioning themselves to better compete against the "Big Tech" encroachment that has defined the last five years of audio retail.
Market Positioning and Digital Commerce Data
The scale of this acquisition is highlighted by the companies’ positions in the broader ecommerce ecosystem. Bose currently ranks as No. 103 in the Digital Commerce 360 Top 1000 Database, which tracks North America’s largest online retailers by annual ecommerce sales. Skullcandy, while smaller in terms of total annual revenue, maintains a solid presence at No. 627.
Beyond traditional retail rankings, the companies are also notable for their adoption of artificial intelligence in commerce. In the Digital Commerce 360 and ReFiBuy AI Commerce Rankings, Bose holds the No. 48 position, while Skullcandy ranks at No. 62. These rankings, found in the Top 1000 Pro with AI Database, reflect the organizations’ investments in automated customer service, personalized product recommendations, and AI-driven supply chain management—technologies that will likely see deeper integration as the companies merge their operational infrastructures.
Official Statements and Executive Vision
Lila Snyder, the CEO of Bose, emphasized that the decision to acquire Skullcandy was rooted in long-term strategic planning rather than short-term market fluctuations. "For more than 60 years, Bose has been committed to delivering incredible audio experiences however and wherever people choose to listen," Snyder stated. She highlighted the advantage of Bose’s status as a privately held company, which provides the executive team with the flexibility to pursue long-term investments without the immediate pressures of quarterly public market earnings.
"As we work to reach even more people, we’re expanding how we do that, not only through Bose products, but through technology partnerships and a growing portfolio of brands," Snyder added. She characterized Skullcandy as an "established, thriving brand" that aligns with Bose’s mission to innovate in the audio space.
Brian Garofalow, CEO of Skullcandy, framed the deal as an evolution of the company’s roots. "We believe this is a win for Skullcandy and our fans," Garofalow noted. "Skullcandy was born on a chairlift in Park City, Utah, over 20 years ago, and we’ve always believed great music should be part of the experiences people love. Joining Bose gives us the opportunity to make those experiences even better by bringing more of their audio expertise and technology to our products."
Broader Market Implications
The acquisition occurs at a time when the consumer audio market is becoming increasingly crowded and competitive. The ubiquity of wireless earbuds and the proliferation of "smart" audio devices have forced traditional audio brands to differentiate themselves through superior sound engineering, battery life, and seamless ecosystem integration.
- Competitive Pressure: The most significant driver of this deal is the assertive growth of competitors such as Apple. With the AirPods line, Apple effectively commoditized premium wireless audio, forcing traditional manufacturers to either consolidate or pivot toward specialized, high-margin products.
- Technological Integration: Samsung and Sony continue to dominate the market by integrating advanced digital assistants and complex noise-cancellation algorithms. By absorbing Skullcandy, Bose gains a secondary, high-volume brand that can serve as a testing ground for new technologies before they are rolled out to the premium Bose product line.
- Customer Lifecycle Management: By combining their digital commerce platforms, Bose and Skullcandy can leverage shared data on consumer behavior. With Bose’s focus on high-end audio and Skullcandy’s focus on the youth market, the combined entity can effectively capture a customer at different stages of their life, from entry-level audio products to high-fidelity, professional-grade gear.
Analysis: A Defensive and Offensive Move
Industry analysts view the acquisition as a dual-purpose strategy. Defensively, it protects Bose’s market share by ensuring that a legacy competitor does not fall into the hands of a broader technology conglomerate. Offensively, it provides Bose with an expanded product portfolio that appeals to demographics that may have previously perceived the Bose brand as too expensive or overly formal.
The success of this merger will likely depend on the operational integration of the two brands. Bose’s challenge will be to scale its technological advancements into Skullcandy’s price-sensitive product tiers without diluting the distinct identities that made both brands successful in their own right. Furthermore, as AI continues to redefine the customer journey, the combined data assets of the two companies—currently reflected in their high rankings in AI-driven commerce tools—will become a critical competitive advantage.
As the audio industry continues to consolidate, the Bose-Skullcandy partnership stands as a prime example of the "brand portfolio" approach to modern retail. By maintaining separate identities under a unified ownership structure, the organizations aim to remain agile, responsive to consumer trends, and technologically ahead of the curve in a world where sound quality is increasingly expected to be accompanied by deep digital integration.