The Dual-Edged Sword of Retail Media: Balancing Growth and Margin Erosion in the Digital Marketplace

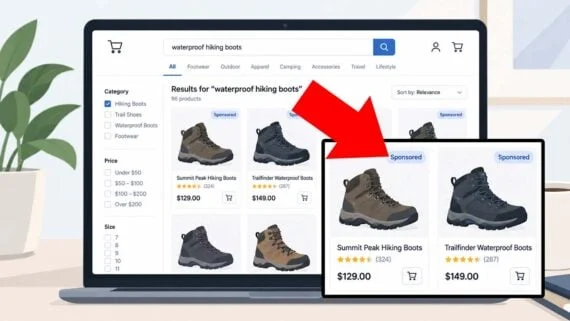
Retail media—the practice of advertising within the digital storefronts of retailers—has rapidly evolved from a supplementary revenue stream into a fundamental pillar of the modern ecommerce ecosystem. At its core, retail media allows brands to purchase sponsored placements directly on platforms where consumers are already actively shopping, such as Amazon, Walmart, and Target. While industry giants like Amazon have set the gold standard for this model, the broader market has expanded into a complex, multi-billion-dollar economy that forces both advertisers and retailers to weigh the benefits of increased visibility against the risks of cannibalized margins.
The scale of this shift is unprecedented. According to a 2025 report published in the Journal of Retailing, global retail media spending surpassed $140 billion in 2024, with the United States alone accounting for $54 billion of that total. Projections from eMarketer suggest that this upward trajectory is far from plateauing; U.S. retail media ad spend is forecast to reach $69.33 billion by 2026, marking a robust 17.9% year-over-year increase from 2025. This rapid expansion reflects a fundamental change in consumer behavior, as shoppers increasingly bypass traditional search engines like Google in favor of direct searches on retailer websites, where purchase intent is high and the path to checkout is frictionless.
The Evolution of the Retail Media Landscape
The origins of the modern retail media surge can be traced back to the mid-2010s, as Amazon began aggressively monetizing its internal search results. Before this shift, brands primarily relied on broad-spectrum digital advertising on social media or search engines to drive traffic to their own standalone websites. However, the realization that "retailer-site traffic" often carried higher conversion rates prompted a strategic pivot. By 2020, the onset of the global pandemic accelerated this transition, as brick-and-mortar retailers shuttered and consumers migrated en masse to digital channels.
Retailers soon recognized that their first-party data—detailed insights into customer purchase history, search patterns, and browsing behavior—was a goldmine for advertisers. Unlike third-party cookies, which are facing extinction due to privacy regulations and browser restrictions, retail media data is gathered directly from the transaction point. This allows for hyper-targeted advertising that feels less like an intrusion and more like a helpful recommendation. However, as the ecosystem matured, the sheer volume of sponsored content began to raise questions regarding market saturation and the long-term sustainability of this model for both publishers and advertisers.
The Advertiser’s Dilemma: Incremental Value vs. Margin Erosion
For an advertiser, the utility of retail media is often measured by the concept of incrementalism. The objective is to identify whether a sponsored placement generates "new" demand—sales that would not have occurred absent the ad.
Consider a scenario where a brand invests $1,000 into a sponsored campaign for a high-end kitchen appliance. If that investment yields $5,000 in sales that result in $1,500 of contribution margin, the campaign is a clear success, providing a $500 net benefit. This represents the ideal state of retail media: the advertiser uses the platform to capture market share or launch a new product, effectively paying for access to a high-intent audience.
However, the economics shift drastically when advertising is forced upon a brand that already commands strong organic visibility. In many marketplaces, the proliferation of sponsored "above-the-fold" placements forces brands into an "advertising tax." If a seller historically ranked number one organically and, due to the introduction of sponsored slots, is now forced to pay for an ad to maintain the same visibility and volume, the advertising spend becomes a defensive cost rather than a growth engine. In this instance, the retailer captures the revenue, but the advertiser loses margin. The Journal of Retailing report highlights this trend as a growing point of friction, noting that many brands are struggling to distinguish between profitable growth and the cannibalization of their own organic sales.
The Retailer’s Balancing Act: Margin vs. Revenue
The risk of retail media is not confined to the brands paying for the placements; the retailers publishing these ads face a unique set of hazards. While advertising revenue is often high-margin, it can inadvertently suppress a retailer’s overall profitability if it interferes with the user experience.
For example, if a retailer features a sponsored product that is less relevant to a shopper than the organic result it displaced, the probability of a conversion drops. If a category page generating $100,000 in monthly sales with a $30,000 gross profit starts to feature paid placements, the retailer might collect $3,000 in ad revenue. If, however, those ads distract or annoy customers to the point where gross profit from product sales dips to $26,000, the retailer has effectively lost $1,000 in total margin despite successfully "monetizing" the page.
Furthermore, the long-term impact on customer trust cannot be overlooked. A site that becomes cluttered with excessive sponsored content often sees a decline in customer satisfaction. If the search experience becomes difficult to navigate, shoppers may migrate to competitors, leading to a permanent decline in the retailer’s customer lifetime value.
Measuring Success in a Data-Driven Era
Because Return on Ad Spend (ROAS) can be a misleading metric—often attributing organic sales to ad campaigns—sophisticated advertisers are moving toward more rigorous testing methodologies. The "last-click" attribution model, which gives credit to the final ad a user saw before buying, is increasingly viewed as obsolete.
Industry leaders are now turning to randomized controlled trials (RCTs) and geo-testing to isolate the impact of their spend. By pausing ads in specific geographic regions or for randomly selected segments of their audience, brands can observe the "lift" in sales to determine if the advertising was truly the catalyst for the purchase. For smaller companies that lack the resources for complex marketing mix modeling, simple comparative analysis—comparing performance during periods of heavy ad spend versus periods of inactivity—has become the standard practice for evaluating whether retail media is providing genuine incremental value.
The Future of Retail Media: Consolidation and Regulation
As the market approaches a projected $70 billion in U.S. spend by 2026, observers anticipate a period of consolidation. The sheer number of retailers attempting to build their own "retail media networks" (RMNs) is creating a fragmented landscape. Brands are becoming increasingly selective, opting to partner only with platforms that offer transparent data and demonstrable incrementality.
Simultaneously, regulatory bodies are beginning to take a closer look at the transparency of these platforms. Issues regarding "pay-to-play" search results, potential antitrust concerns, and the clarity of ad labeling are topics of ongoing discussion among industry analysts and policymakers. If the industry fails to self-regulate or ensure that its practices remain fair to both sellers and consumers, it may face intervention that could reshape the current model.
Ultimately, retail media is not inherently a zero-sum game. It is a powerful tool for discovery when executed with precision and a focus on the customer experience. However, the data makes one thing clear: success in the retail media age requires moving beyond vanity metrics. Brands must focus on incrementality, and retailers must ensure that their pursuit of advertising revenue does not come at the expense of the core shopping experience. As the market continues to mature, the winners will be those who balance the short-term gains of ad sales with the long-term health of their retail ecosystem.
Related posts: