AI-Generated Receipts Surge to Comprise Over 70% of Flagged Expense Fraud, Redefining Corporate Compliance

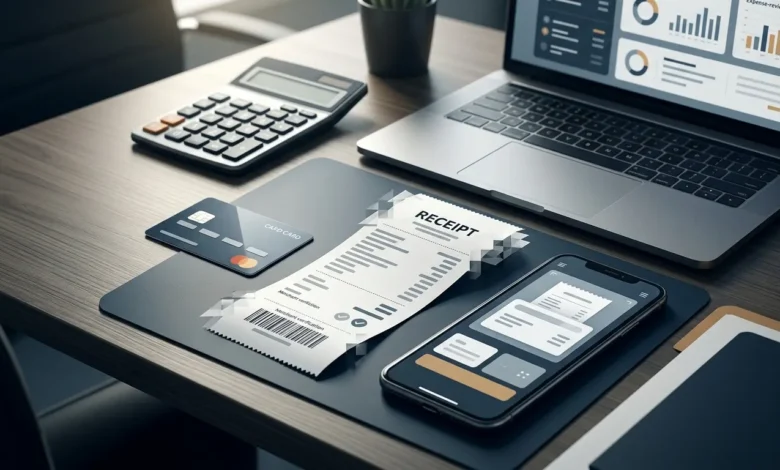
The landscape of corporate expense management has undergone a profound and rapid transformation, driven by the widespread accessibility of generative artificial intelligence. According to recent platform data released by expense-management vendor AppZen, AI-generated receipts now account for 70.8% of all flagged fraudulent expense submissions. This represents a staggering escalation from just 0% in March 2025.
The empirical foundation of this finding is drawn from a targeted detection dataset identifying 1,471 AI-generated fake receipts submitted by 745 distinct employees across 174 companies. These fraudulent submissions collectively claimed $148,143 in fabricated corporate reimbursements. While this data reflects a specific slice of platform-detected anomalies rather than an overarching estimate of total global workplace fraud, it signals an unprecedented shift in the mechanics of occupational deception.
Parallel insights from the employee demographic reinforce these technological concerns. A comprehensive survey conducted by Atomik Research between May 5 and May 8, 2026, commissioned by expense platform Emburse and reported by PYMNTS, revealed that 40% of surveyed U.S. workers and 29% of U.K. workers openly admitted to utilizing artificial intelligence to generate fake business-expense receipts. Breaking down the methodology of these respondents, 40% stated they leveraged company-funded AI tools for the fabrication, while 9% engineered their own custom applications explicitly for the purpose of forging financial documentation.
For small-business finance teams, corporate comptrollers, and enterprise auditors alike, the operational reality is stark: a traditional receipt image can no longer be accepted as reliable, self-authenticating proof of a legitimate business purchase. While this evolution does not imply that the majority of all corporate expense claims are fraudulent, nor that artificial intelligence is the sole vector of financial malfeasance, it establishes that AI-generated documents have decisively usurped older, template-based methods as the dominant format for detected expense fraud. Consequently, foundational internal controls relying heavily on visual inspection are rapidly losing their efficacy.
Chronology and Evolution of Synthetic Expense Fraud
To fully understand the current crisis in expense validation, it is necessary to examine the rapid chronology of how bad actors adopted generative artificial intelligence tools. Prior to early 2025, corporate expense fraud relied primarily on rudimentary manipulation methods. Employees seeking illicit reimbursements typically utilized online document templates, altered PDF statements, or manually edited existing receipt imagery using basic photo-retouching software. These legacy methods invariably left detectable forensic markers, including misaligned fonts, anachronistic layout geometries, inconsistent pixel densities, and visibly altered numerical totals.
By late 2024 and early 2025, the barrier to entry for generating synthetic media began to drop precipitously with the commercial proliferation of advanced text-to-image and document-generation models. However, platform data indicates that the true tipping point occurred in the spring of 2026. According to industry reporting by Accounting Today based on AppZen’s tracking metrics, AI-generated fraudulent receipts officially surpassed legacy template-based forgeries in April 2026.
This crossover point marked the moment when generative artificial intelligence matured to the point of effortlessly replicating hyper-realistic thermal paper textures, complex itemized tax breakdowns, authentic merchant branding, and localized point-of-sale formatting. Once synthetic generation became cheap, fast, and virtually indistinguishable from genuine documentation to the naked eye, the volume of AI-backed submissions accelerated exponentially, culminating in the 70.8% saturation rate observed by mid-May 2026.
Anatomizing the Threat: Intent and Behavioral Profiles
Data captured through self-reported employee surveys provides crucial context regarding the psychological and operational motivations driving this trend. The Emburse study categorizes the admitted users of AI receipt generation into distinct operational risk profiles, each carrying unique compliance challenges for internal auditors.
Among the workers who confessed to deploying artificial intelligence for receipt fabrication, 19% admitted to generating completely fictitious transactions for goods and services that were never actually purchased. This segment represents deliberate, premeditated corporate theft. Another 15% reported utilizing AI to inflate the monetary value of a genuinely incurred business expense—a practice designed to skim additional capital from standard travel, client entertainment, or office supply budgets. Finally, 6% of respondents stated they used AI tools to recreate a genuinely lost receipt for an actual business purchase where documentation had been misplaced.
This fragmentation of intent creates a complex governance dilemma for corporate finance departments. A rigid, zero-tolerance policy that treats all three behavioral categories identically risks penalizing honest employees who made administrative errors or lost paperwork in the same manner as hardened fraudsters executing deliberate financial crimes. Conversely, failing to scrutinize these discrepancies exposes the organization to systemic leakage.
Furthermore, the quantitative profile of AI-generated fraudulent claims exhibits a distinct strategic design aimed at evading detection algorithms. AppZen’s dataset indicates that AI-generated fakes cluster around an average claim size of approximately $100, with a median value of just $32. This stands in stark contrast to older, template-based fraudulent receipts, which maintained an average value of $182.
This divergence highlights a calculated psychological threshold: fraudsters are increasingly deploying high-volume, low-dollar synthetic claims designed explicitly to slide beneath automated management approval thresholds and avoid the intense, multi-tiered scrutiny typically reserved for high-value travel or capital expenditure reimbursements.
The Collapse of Traditional Visual-Review Workflows
For decades, the standard corporate reimbursement workflow has relied on a foundational assumption: that a visual receipt image serves as a faithful, immutable record of a completed commercial transaction. Under this legacy framework, an employee incurs an expense, uploads a digital scan or photo of the receipt, and a line manager, department head, or bookkeeper visually inspects the document for a plausible vendor name, date, and matching total. Upon visual confirmation, the claim is approved, reimbursement is executed, and the record is archived for tax compliance and auditing purposes.
Synthetic artificial intelligence has severely compromised the initial link in this verification chain. Because modern generative tools can produce flawless merchant-style typography, accurate alignment, and contextually appropriate line items without requiring technical graphic design expertise, the visual indicators that once betrayed forged documents have effectively vanished.
When a manager is presented with a crisp, professionally formatted digital receipt for a $32 lunch or a $45 ride-share, there are few visual cues remaining to justify delaying approval for further investigation. This reduction in the skill barrier required to produce convincing falsifications has democratized financial fraud within organizations, enabling non-technical personnel to systematically siphon funds through routine, everyday expense categories.
The Vulnerability of Small-Business Finance Teams
While multinational corporations and large enterprises frequently deploy sophisticated, multi-layered fraud detection technologies, real-time transaction monitoring systems, and dedicated internal audit teams, small and mid-sized businesses (SMBs) operate in a fundamentally different risk environment.
In a typical small business, expense oversight is rarely the responsibility of a dedicated forensic accountant. Instead, the duty often falls to a solo business owner, an office manager, or an outsourced bookkeeper who must balance receipt verification against a myriad of competing operational demands, including payroll processing, accounts payable, vendor management, and business scheduling. Consequently, an overburdened administrator evaluating dozens of low-dollar claims has limited capacity to investigate the authenticity of a minor $32 coffee purchase or a localized transit receipt.
This operational vulnerability is frequently compounded by structural practices such as shared corporate credit cards, informal managerial approval chains, and delayed post-facto bookkeeping reviews. When low-dollar synthetic claims are submitted repeatedly by the same individual over a period of weeks or months, each individual submission may appear entirely benign in absolute isolation. However, viewed collectively over a longer time horizon, these micro-frauds accumulate into significant corporate financial loss.
Beyond the immediate cash flow impact of fraudulent reimbursements, synthetic receipts introduce severe long-term accounting and tax liabilities. Fabricated or misclassified expense records distort corporate general ledgers, compromise job-cost reporting accuracy, invalidate client billing schedules, and introduce vulnerabilities into annual tax filings. Rectifying these systemic errors after the fact requires forensic accounting hours that resource-constrained small businesses simply do not possess.
Strategic Remediation: Upgrading Internal Controls for the AI Era
The rapid evolution documented by AppZen and Emburse mandates an immediate reevaluation of corporate expense policies. Industry experts emphasize that visual inspection of receipt imagery can no longer serve as the primary line of defense in an institutional approval workflow. To effectively mitigate synthetic expense fraud without establishing burdensome bureaucratic bottlenecks, organizations must transition toward data-centric verification models.
First, finance departments must implement automated transaction-matching protocols. Rather than relying on static images, expense management platforms should directly cross-reference corporate credit card feeds, bank transaction ledgers, and automated clearing house (ACH) logs to verify that a physical charge actually occurred at the stated merchant for the exact claimed amount on the documented date.
Second, organizations must prioritize behavioral analytics and frequency monitoring over static document verification. Because AI-generated fraud often relies on recurring, low-dollar submissions, algorithmic tracking of employee claim frequencies, preferred merchant clusters, and cyclical reimbursement patterns can successfully flag anomalies that visual inspections miss.
Third, companies must establish unambiguous, formalized corporate policies regarding the use of artificial intelligence in administrative workflows, explicitly defining the administrative penalties for submitting synthetic or artificially altered documentation. Furthermore, clear protocols must be established for handling genuine lost receipts, ensuring that employees have a transparent, non-fraudulent pathway to document legitimate expenses without resorting to generative workarounds.
Broader Industry Implications and Future Outlook
The empirical rise of synthetic expense fraud from a statistical baseline of zero to dominating over 70% of flagged platform anomalies in little more than a year serves as a watershed moment for corporate governance. It underscores a broader, cross-industry reality: the proliferation of generative artificial intelligence is forcing an adversarial race between automated creation tools and automated verification technologies.
As synthetic media generation becomes increasingly sophisticated, the traditional pillars of trust upon which modern accounting practices were built—paper trails, digital scans, and visual attestations—are no longer sufficient safeguards. Moving forward, the resilience of corporate finance operations will depend entirely on their ability to decouple verification from document appearance. By embedding independent data matching, rigorous merchant verification, behavioral pattern analysis, and robust digital governance into the core of daily operations, businesses can reestablish control over their reimbursement ecosystems and safeguard their financial integrity against the accelerating tide of synthetic fraud.