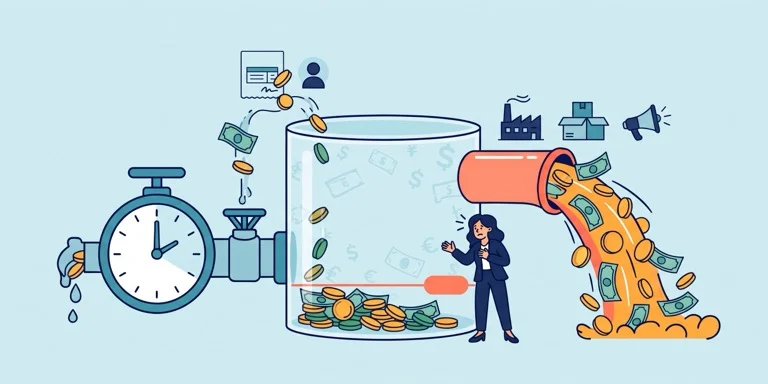
The champagne is flowing in the executive suite following a record-breaking month of sales, yet the company bank account tells a terrifyingly different story when an unexpected vendor invoice arrives. This paradox strikes thousands of dynamic, rapidly expanding enterprises every year. Business founders frequently encounter a harsh economic reality: profitability and positive revenue growth do not automatically guarantee liquidity.
The Core Phenomenon: Understanding the Liquidity Gap
At the heart of this financial disconnect lies a fundamental misunderstanding of accounting mechanics. Traditional business education and cultural narratives often equate financial distress exclusively with business failure or poor product-market fit. However, corporate financial data demonstrates that cash flow crunches frequently target thriving organizations experiencing high-velocity growth.
The underlying issue stems from a temporal mismatch. Revenue and cash operate on two entirely distinct operational calendars. Under standard accrual accounting principles, revenue is officially recognized and recorded the exact moment a transaction is completed or a service is rendered, regardless of when the physical funds change hands. Cash, conversely, represents the actual liquid currency currently sitting within a corporate depository institution.
For many business-to-business (B2B) and retail operations, these two milestones are separated by significant time intervals. A logistics firm might ship a major commercial order in January, booking the transaction as January revenue. However, if the client operates under standard net-30 or net-60 payment terms, the actual funds may not materialize in the company’s bank account until February or March. Meanwhile, operational expenses—such as payroll, commercial rent, utilities, and raw material costs—adhere strictly to their own immediate payment schedules.
Chronology of a Cash Crunch: How Profitable Companies Stumble
To comprehend how a thriving enterprise faces insolvency symptoms, financial analysts often look at the standard operational lifecycle of inventory-dependent businesses. The timeline of a typical cash crunch unfolds through a predictable sequence of operational milestones:
- The Sales Surge (Day 1): The enterprise closes a massive commercial deal or experiences an unprecedented retail surge. Sales figures spike, boosting morale and generating enthusiastic reports for stakeholders.
- The Fulfillment Outlay (Days 1–15): To meet this heightened demand, the company must immediately purchase raw materials, pay manufacturing overhead, and invest heavily in customer acquisition campaigns. Crucially, suppliers generally demand upfront payments or strict short-term settlement windows. Cash rapidly evacuates the corporate bank accounts.
- The Delivery and Invoicing Phase (Days 16–30): Products are successfully manufactured, shipped, and delivered to the end consumer. Official invoices are generated and dispatched, formally recording the transaction as recognized revenue on the corporate balance sheet.
- The Waiting Period (Days 31–90): The company holds zero physical cash from the transaction while awaiting payment settlement from the client base. During this window, subsequent payroll cycles, tax obligations, and secondary supplier invoices fall due.
- The Liquidity Crisis Point: If incoming cash collections fail to overlap neatly with outgoing operational liabilities, the business experiences an acute cash shortage despite maintaining impressive top-line revenue growth on paper.
Financial Analysis: Why Rapid Growth Exacerbates the Problem
Industry researchers and corporate restructuring specialists frequently observe a counterintuitive axiom: the faster a company grows, the more acute its immediate cash vulnerability becomes.
When an organization scales operations, its working capital requirements multiply exponentially. Every incremental unit of growth demands advance capital allocation. A company must fund larger inventory orders, hire additional personnel, expand physical or digital infrastructure, and elevate marketing expenditures long before the resulting revenue streams are fully realized and collected.
According to macroeconomic studies on small and medium-sized enterprises (SMEs), inadequate cash flow management consistently ranks among the leading causes of business closures, outranking even weak market demand. Financial analysts emphasize that growth is fundamentally purchased with upfront cash. Without robust revolving credit facilities, substantial cash reserves, or tightly optimized collection cycles, scaling enterprises effectively finance their own expansion to the brink of insolvency.
Industry Responses and Modern Solutions
As awareness of this systemic issue spreads across entrepreneurial communities, corporate advisors, financial technologists, and SaaS providers are altering how businesses approach liquidity management. Modern financial management platforms—such as automated accounting suites, real-time banking feeds, and integrated invoicing ecosystems like Xero—have fundamentally shifted how organizations monitor their fiscal health.
Industry experts stress that combating the revenue-cash gap requires a two-pronged strategic approach focusing on velocity and visibility.
- Accelerating Cash Velocity: Organizations are increasingly tightening their accounts receivable protocols. By transitioning away from archaic manual invoicing toward automated digital billing systems, companies reduce administrative friction. Implementing strict credit checks, offering minor financial incentives for early payments, and aggressively tracking overdue accounts ensure that earned capital returns to the corporate treasury with minimal delay.
- Enhancing Financial Visibility: Forward-looking visibility tools allow modern businesses to project cash positions weeks and months into the future. By synchronizing bank feeds directly with invoicing and expense platforms, executives gain a real-time, consolidated dashboard of their liquidity standing. This proactive oversight replaces retrospective panic with predictive planning, enabling leadership teams to anticipate seasonal troughs and structural deficits before they trigger operational disruptions.
Broader Implications for the Modern Economy
The growing disconnect between top-line revenue and actual cash reserves highlights a critical evolution in corporate financial literacy. As global commerce accelerates and transaction structures grow increasingly complex, relying solely on traditional profit-and-loss statements is no longer sufficient for sustainable enterprise management.
Economists and commercial advisors emphasize that business education curricula must increasingly prioritize working capital mechanics over abstract theoretical accounting. By acknowledging that revenue is merely a promise of future liquidity rather than an immediate resource, founders and financial controllers can construct resilient operational buffers. Ultimately, mastering the timing between earning and banking remains the definitive differentiator between enterprises that merely scale temporarily and those that achieve enduring, long-term commercial viability.